Retiring at 55: Your Biggest Tax Decision May Be Happening Now
Health insurance is one reason where you save can matter as much as how much you save.
WEEKLY BLOG 09/21/26-09/25/26
Picture being 47 with a good income, a growing retirement account, and a goal of making work optional at 55. You save consistently. You check the balances. You run the numbers to see how much more you need.
Naturally, most of your attention goes to the amount. Get to the right number, and retirement becomes possible.
But the balance is only part of the story. Two households can arrive at retirement with the same amount on their statements and very different options for turning those savings into a paycheck.
For someone retiring at 55, the biggest tax decision may not be how much to convert to a Roth. It may be how to pay for health insurance until Medicare generally becomes available at 65. For households buying coverage through the Affordable Care Act marketplace, the income they report can substantially affect that cost.
And the ability to manage that income can depend on decisions made years earlier. Not just what you invested in, but which accounts you used to save.
A low tax bracket is only part of the math
I like Roth conversions. I just don’t like evaluating them as though the income tax is their only cost.
The basic trade is straightforward. Move money from a pretax retirement account into a Roth, recognize the taxable amount now, and position that money for potentially tax-free withdrawals later. That can be attractive when today’s tax cost is lower than the cost you expect in the future.
But health insurance adds another calculation.
The enhanced federal premium tax credits expired at the end of 2025. Under current law, households with income above 400% of the federal poverty level are once again ineligible for the federal credit. Above that limit, the assistance does not simply shrink. Eligibility ends.
For 2027 coverage, that limit is $86,560 for a two-person household in the 48 contiguous states and Washington, D.C. The calculation uses the 2026 poverty guideline of $21,640 because marketplace credits use the guidelines in effect when open enrollment begins. Different household sizes have different limits, as do Alaska and Hawaii.
That $86,560 is not a spending limit. It is not an account-balance limit. And it is not taxable income after taking the standard deduction.
The marketplace uses household modified adjusted gross income. That includes investment income and most taxable retirement-account withdrawals, with certain additions such as tax-exempt interest.
You can have room left in a relatively low income-tax bracket and very little room left before losing a valuable insurance credit. A plan that only looks at the bracket can miss the more expensive part of the decision.
Two couples, similar balances, different insurance bills
Consider two hypothetical couples. Both retired at 55 and are now 58. Both file jointly, have no dependents, and live in the same area. Each has $3 million across their investment and retirement accounts.
For this example, each household raises $140,000 of cash during 2027, before paying income taxes and health-insurance premiums.
Couple A has $2.7 million in pretax retirement accounts and $300,000 in a taxable brokerage account. In the withdrawal strategy we are illustrating, they take $140,000 from fully pretax retirement savings.
Couple B has $1.5 million in pretax accounts, $500,000 in Roth accounts, and $1 million in a taxable brokerage account. They sell $115,000 of investments with a $75,000 adjusted cost basis. That produces a $40,000 capital gain. They also receive $25,000 of interest and dividends.
Both have raised $140,000. But assuming no other income or adjustments, Couple A has $140,000 of household income for ACA purposes. Couple B has $65,000. The difference is that recovering the cost basis of an investment is not the same as recognizing a gain.
Assume both couples purchase marketplace coverage for the full year and otherwise meet the eligibility requirements. Also assume the benchmark plan costs $24,000 annually and both enroll in it. That premium is an illustration, not a quote or forecast. The benchmark is generally the second-lowest-cost Silver plan available to the household.
Here is the result.
|
Hypothetical 2027 comparison |
Couple A |
Couple B |
|
Total investment and retirement-account balances |
$3,000,000 |
$3,000,000 |
|
Cash raised before taxes and insurance premiums |
$140,000 |
$140,000 |
|
Household income for ACA purposes |
$140,000 |
$65,000 |
|
Annual benchmark-plan premium |
$24,000 |
$24,000 |
|
Federal premium tax credit |
$0 |
$17,357 |
|
Premium cost after the federal credit |
$24,000 |
$6,643 |
Illustrative calculations exclude state assistance, income taxes, deductibles, and other out-of-pocket medical costs. For 2027, the expected contribution toward benchmark premiums is 10.22% of household income between 300% and 400% of the poverty level. Couple B’s $65,000 falls within that range: $65,000 × 10.22% = $6,643.
That is a $17,357 difference in one year’s health-insurance premiums under these assumptions.
This does not prove that Couple B made better decisions throughout their working lives. Equal account balances are not equal after-tax wealth, and the example does not measure the value of the deductions Couple A received along the way. Couple A also still has options, including its taxable account.
The point is narrower. The source of a retirement paycheck can change the cost of health insurance, even when the amount of cash raised is identical.
Getting to the money is not the same as controlling the income
There is an important distinction here for anyone retiring at 55.
The “rule of 55” can allow distributions from the relevant former employer’s retirement plan without the usual 10% early-distribution tax when separation occurs during or after the calendar year the employee turns 55. That exception does not apply to IRAs. Our example assumes Couple A qualifies and its plan permits the withdrawals.
That can solve an access problem. It does not make a fully pretax withdrawal disappear from the income calculation.
A taxable account works differently because a sale can include both gain and a return of your invested money. That is why cost basis matters, not just the account’s market value.
There are also traps inside the phrase “tax-free.” A long-term capital gain taxed at a 0% federal rate still counts toward marketplace income. Tax-exempt municipal-bond interest counts, too. Avoiding federal income tax does not necessarily mean avoiding an effect on your insurance credit.
A mix of accounts can give a household more control over how much income its spending creates. It does not create unlimited control. But it can create choices that a balance alone will not reveal.
The Roth conversion still has to earn its place
Now bring the conversion back into the picture.
Suppose Couple B, with its $65,000 of household income, completes a $25,000 fully taxable Roth conversion. Household income becomes $90,000, above the $86,560 federal limit.
Under our assumptions, the entire $17,357 federal credit disappears. The conversion creates an income-tax obligation and an additional health-insurance cost, even though it does not put another dollar into the couple’s spending account.
That is why “we have room in the tax bracket” is the beginning of the analysis, not the conclusion.
Even below the cliff, additional income can reduce assistance. Within the 300%-to-400% income band in 2027, an extra $1,000 of income can reduce a positive federal credit by $102.20, assuming everything else stays the same. That cost sits alongside the income tax.
None of this means conversions are bad. It means they need to be priced correctly.
A household with substantial pretax savings may reasonably accept a higher current cost to reduce future taxable withdrawals. It may make sense to convert more in a year when the federal credit is already unavailable. Or it may make sense to preserve assistance now and revisit conversions later.
Those are alternatives to compare, not instructions to follow automatically. The goal is not the smallest tax bill this year or the largest subsidy. It is a sensible long-term result after considering both.
This is why the work starts in your 40s
The lesson for someone who is still working is not to stop contributing to a pretax 401(k).
Pretax contributions can provide valuable current tax savings. Roth contributions give up that exclusion today in exchange for different treatment later. Paying tax during your highest-earning years simply to build a Roth account is not automatically the better trade.
The lesson is to make the account decision deliberately.
You may be able to maximize pretax retirement contributions while also building a taxable account. A Roth option may fit some years better than others. The right combination depends on current taxes, future spending, employer benefits, and the rest of the household’s finances.
For someone receiving restricted stock units, this conversation also includes what happens after the shares arrive. With typical public-company RSUs that vest and settle together, the stock’s value is generally included in wages and establishes its tax basis. Selling shortly afterward may produce relatively little additional gain or a small loss, depending on the price movement.
Those proceeds can become part of a diversified taxable account intended for early retirement. Holding the employer stock for another decade is a different decision, with different investment risks and potentially much more embedded gain. The future usefulness of that account depends on more than its balance.
Accurate basis records matter, too. Eventually, the useful question is not just how much the account is worth. It is which shares can be sold, how much cash those sales will produce, and how much gain they will recognize.
Roth savings and health savings accounts can add flexibility, but their rules still matter. Not every Roth withdrawal at 55 is automatically tax- and penalty-free. Contributions, conversions, and earnings have different withdrawal rules. HSA distributions for qualified medical expenses can be tax-free, but ordinary marketplace premiums generally are not qualified HSA expenses unless an exception applies.
The accounts are not interchangeable. That is precisely why having a thoughtful combination can be useful.
Plan around flexibility, not a permanent threshold
Someone reading this at 47 should not build an entire retirement plan around an $86,560 limit.
That is a current-law number for 2027 coverage, not a promise about what the rules will look like eight or ten years from now. The expiration of the enhanced credits is itself a reminder that these rules can change.
I would not take the $17,357 difference in our example, multiply it by ten, and present the result as guaranteed savings. Premiums can change. Household circumstances can change. Selling investments uses up basis, and the same withdrawal strategy may not work equally well every year.
What I would plan around is the ability to adapt.
That matters after Medicare begins, too. Medicare has its own income-related premium adjustments, generally using tax information from two years earlier. Waiting until 65 does not remove health-care costs from the conversion calculation. It changes the calculation.
There are also households for whom the ACA argument is less relevant. If pensions, consulting income, or necessary withdrawals already put income comfortably above the federal limit, there may be no federal credit for a conversion to eliminate. If you are enrolled in employer retiree coverage, you generally cannot receive the marketplace premium tax credit for yourself while enrolled in that coverage.
For those households, conversions may deserve a larger role. Preserving a benefit you were never eligible to receive is not a planning objective.
Put insurance and tax planning on the same calendar
For New Jersey readers, open enrollment for 2027 coverage runs from November 1, 2026, through January 31, 2027. That creates a practical opportunity to review insurance and retirement income together.
New Jersey also has its own assistance program. For 2026, New Jersey Health Plan Savings extends to eligible households with income up to 600% of the federal poverty level. Losing the federal credit does not necessarily mean losing every form of assistance. The applicable state rules and actual 2027 plan quotes need to be included before making a decision.
Keep the income year straight. A conversion completed in 2026 affects the calculation for 2026 coverage. A conversion completed in 2027 affects 2027. And leaving work halfway through a year does not erase the wages earned before retirement. Marketplace savings depend on income for the coverage year, not just what comes in after the last paycheck.
I would also leave breathing room rather than design a plan that works only if every dividend and capital-gain distribution lands exactly where expected.
Advance credits are reconciled against actual eligibility when the tax return is filed. For tax years after 2025, there is no repayment cap on excess advance credits. An income surprise can therefore become a repayment obligation.
This is work to do before the transaction, not after the tax documents arrive.
The balance is not the plan
A useful early-retirement plan should show more than a projected portfolio value and a withdrawal percentage. It should show where the money will come from, what income those withdrawals will create, and how that income affects the rest of the household’s costs.
A Roth conversion can be a good strategy. Preserving an insurance credit can be a good strategy. They do not automatically work well together.
For someone retiring at 55, the first decision may be how to fund the years before Medicare without making health insurance unnecessarily expensive. The conversion decision comes after that analysis.
And for someone still in their 40s, the work starts now. The decisions about your 401(k), company stock, and taxable savings are helping determine the choices you will have later.
The plan is the product, not the portfolio. The balance tells you how much you have. The plan tells you how it can support the life you want.
For educational purposes only, not individualized tax, investment, or insurance advice. The examples are hypothetical, are not insurance quotes, and do not represent actual clients or a recommended account allocation. They illustrate one year of federal premium-tax-credit calculations, not a lifetime comparison of savings strategies. Rules and figures reflect information available as of September 21, 2026. Actual eligibility, premiums, taxes, and state assistance depend on individual circumstances and may change.
Sources
Internal Revenue Service, “Questions and Answers on the Premium Tax Credit.” Federal eligibility requirements, household-income definitions, poverty-guideline timing, and reconciliation of excess advance credits. https://www.irs.gov/affordable-care-act/individuals-and-families/questions-and-answers-on-the-premium-tax-credit
U.S. Department of Health and Human Services, ASPE, “2026 Poverty Guidelines.” The 2026 guideline for a two-person household in the 48 contiguous states and Washington, D.C., is $21,640. Four hundred percent is $86,560. https://aspe.hhs.gov/poverty
Internal Revenue Service, Revenue Procedure 2026-26. Establishes the 2027 applicable-percentage table, including the 10.22% contribution percentage between 300% and 400% of the federal poverty level. https://www.irs.gov/pub/irs-drop/rp-26-26.pdf
Internal Revenue Service, Publication 974, “Premium Tax Credit.” Benchmark-plan definitions and the credit-calculation framework. https://www.irs.gov/publications/p974
HealthCare.gov, “What to Include as Income” and “Health Coverage for Retirees.” Marketplace income treatment, coverage before Medicare, and the effect of enrollment in employer retiree coverage. https://www.healthcare.gov/income-and-household-information/income/
Internal Revenue Service, “Retirement Topics – Exceptions to Tax on Early Distributions.” Separation-from-service exception beginning in the calendar year an employee turns 55, and its exclusion from IRA distributions. https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-exceptions-to-tax-on-early-distributions
Internal Revenue Service, Topic No. 409, “Capital Gains and Losses,” and Publication 551, “Basis of Assets.” Sale proceeds, adjusted basis, capital gains, and identification of securities sold. https://www.irs.gov/publications/p551
Internal Revenue Service, “Roth Account in Your Retirement Plan” and Publication 590-B, “Distributions from Individual Retirement Arrangements.” Pretax and Roth tax treatment, conversion income, and qualified distributions. https://www.irs.gov/publications/p590b
Internal Revenue Service, Publication 5992, “Equity (Stock)-Based Compensation Audit Technique Guide.” Restricted stock units and the income treatment of stock-settled awards. https://www.irs.gov/pub/irs-utl/equitystockbasedcompensationaudittechniquesguide.pdf
Internal Revenue Service, Publication 969, “Health Savings Accounts and Other Tax-Favored Health Plans.” Tax treatment of HSA distributions and limitations on treating insurance premiums as qualified medical expenses. https://www.irs.gov/publications/p969
Social Security Administration, Program Operations Manual System, HI 01101.010, “Modified Adjusted Gross Income.” Medicare income-related premium adjustments and the general two-year lookback. https://secure.ssa.gov/poms.nsf/lnx/0601101010
Get Covered New Jersey, “Get Financial Help.” New Jersey Health Plan Savings and published 2026 state-assistance eligibility. https://nj.gov/getcoverednj/financialhelp/gethelp
New Jersey Department of Banking and Insurance, Bulletin No. 26-07, August 10, 2026. Confirms the November 1, 2026, through January 31, 2027, open-enrollment period for New Jersey’s 2027 individual-market coverage. https://www.nj.gov/dobi/bulletins/blt26_07.pdf
Disclosure
If converting a Traditional IRA to a Roth IRA, you will owe ordinary income taxes on any previously deducted Traditional IRA contributions and on all earnings. A conversion may place you in a higher tax bracket than you are in now. Because Roth IRA conversions may not be appropriate for all investors and individual situations vary we suggest that you discuss tax issues with a qualified tax advisor.
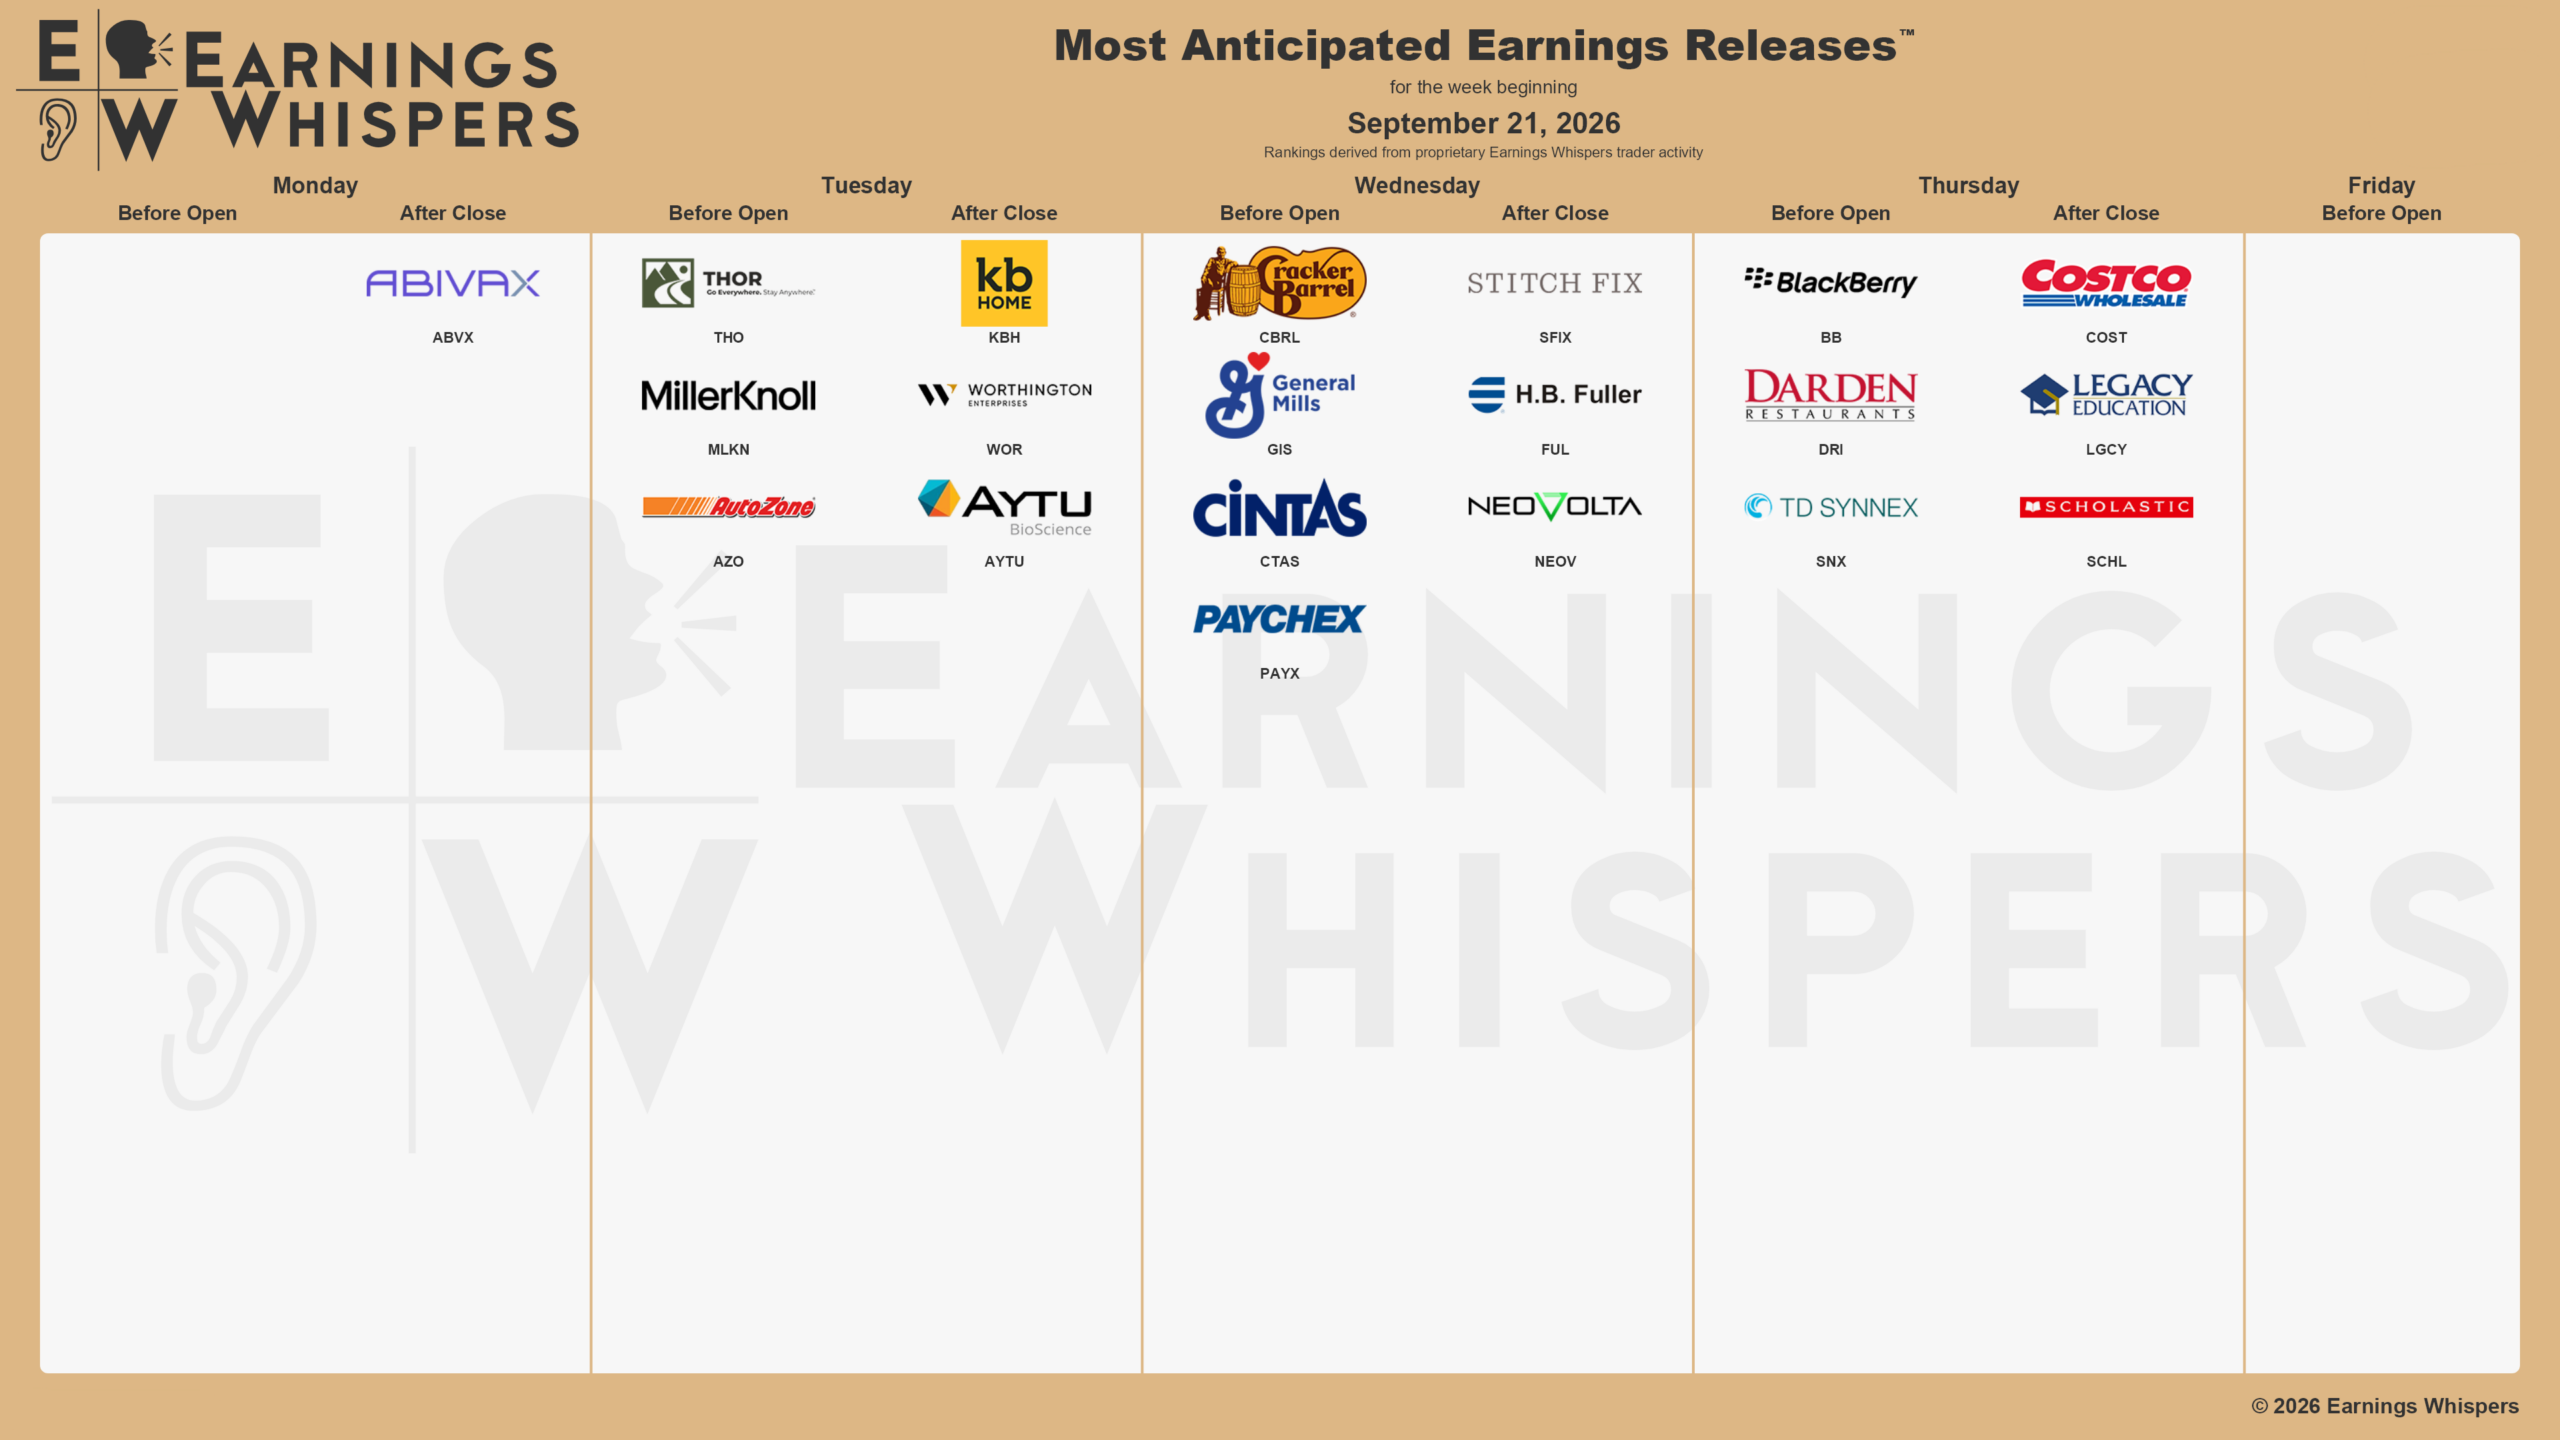
Stock Market Calendar This Week:
| Time (ET) | Report |
| Monday, Sep. 21 | |
| 9:00 AM | Fed speech: |
| Tuesday, Sep. 22 | |
| 1:00 PM | Federal Reserve Bank of Richmond President Thomas Barkin speaks to the CFA Society Baltimore |
| Wednesday, Sep. 23 | |
| 9:45 AM | US Flash Manufacturing PMI |
| 9:45 AM | US Flash Services PMI |
| 10:05 AM | Fed speech: Fed governor Michael Barr |
| Thursday, Sep. 24 | |
| 8:30 AM | Weekly Jobless Claims |
| 8:30 AM | Economic Club of Washington, DC event with Federal Reserve Bank of Richmond President Thomas Barkin |
| 10:00 AM | New Home Sales |
| 10:10 AM | Fed speech: Philadelphia Fed president Anna Paulson |
| 11:00 AM | Kansas City Fed Survey |
| Friday, Sep. 25 | |
| 5:15 AM | Fed speech: New York Fed President John WIlliams |
| 8:30 AM | Durable Goods |
| 10:00 AM | U. Michigan Final Consumer Survey |
| 2:00 PM | Fed speech: Cleveland Fed President Beth Hammack |
About Amit: I am a first generation American, the son of a working-class Indian family, and I lived through my parents’ struggle to find their place in this country, to put down roots that would sustain them as well as their children in a new land. As they encouraged me to excel in school and fostered my hobbies and interests, I was keenly aware of the dynamic between them. I understood that there was a difference between where they came from individually and where we were now. They worked hard in their individual capacities, but they weren’t always on the same page about financial issues – and that can make or break a family’s future. I didn’t know it at the time, but this laid the groundwork for my passion towards financial services and helping families succeed.
IMPORTANT NOTICE AND DISCLOSURE
The information and material contained in this communication is confidential and intended for the recipient addressee named. If you are not the intended recipient please delete the message and notify the sender immediately.
NewEdge Advisors, LLC is an Investment Adviser registered with the Securities and Exchange Commission. Any information provided has been obtained from sources considered reliable, but we do not guarantee the accuracy or the completeness of any description of securities, markets or developmentsmentioned. As a precautionary measure, we cannot rely on e-mail requests to authorize, direct or effect the purchase or sale of any security, wire transfer, or to affect any other transactions. Such requests, orders, or other instructions sent by email should be confirmed verbally, prior to their anticipated execution. We are unable to ensure email sent to you from us, or sent from you to us will be received. Please contact us at 845-652-3449 if there is any change in your financial situation, needs, goals or objectives, or if you wish to initiate any restrictions on the management of the account or modify existing restrictions. Additionally, we recommend you compare any account reports from NewEdge Advisors LLC with the account statements from your Custodian. Please notify us if you do not receive statements from your Custodian on at least a quarterly basis. Our current disclosure brochure, Form ADV Part 2, is available for your review upon request. This disclosure brochure, or a summary of material changes made, is also provided to our clients on an annual basis. This material was prepared with the assistance of AI. All content has been reviewed, edited, and approved by Forefront Wealth Planning prior to use. This is general education and not a substitute for personalized tax, legal, or investment advice. Your situation should be reviewed with the appropriate professionals before taking action. Advisory services offered through NewEdge Advisors, LLC, a registered investment adviser.