The September 15 Deadline That Doesn’t Forgive Guesswork
Where did your estimated tax number actually come from?
WEEKLY BLOG 09/14/26 – 09/18/26
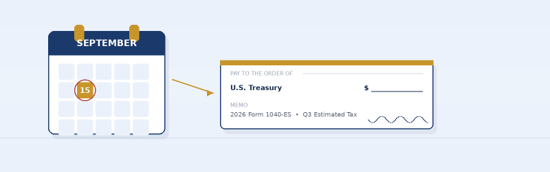
There is something uniquely unpleasant about writing a large check to the IRS when you are not entirely sure whether the number is right.
For W-2 employees, taxes are mostly happening quietly in the background. Money comes out of each paycheck, and by the time April arrives, much of the bill has already been paid.
For a physician receiving 1099 income, a consultant, a business owner, or anyone else whose income does not come with enough tax withholding attached, the experience can look very different.
Four times a year, there is a date on the calendar.
And on September 15, the third estimated federal tax payment for 2026 is due.
The question is: where did your number come from?
“That’s What I Paid Last Quarter” Is Not a Tax Projection
The IRS operates on a pay-as-you-go system. For estimated tax purposes, the year is divided into four payment periods, with the third payment due September 15. If you do not pay enough during the year, an underpayment penalty may apply even if you ultimately receive a refund when you file your return.
That does not mean every business owner needs to know their final tax bill down to the dollar by September.
There are rules designed to provide some predictability.
Generally, an individual who expects to owe at least $1,000 after withholding and credits may need to make estimated payments. In many cases, avoiding an estimated-tax penalty means paying enough during the year to cover at least 90% of the current year’s tax or 100% of the prior year’s tax. For certain higher-income taxpayers, the prior-year threshold increases to 110%.
|
To Generally Avoid an Underpayment Penalty |
Pay at Least |
|
Based on this year’s expected tax |
90% of the current year’s tax |
|
Based on last year’s tax (most taxpayers) |
100% of the prior year’s tax |
|
Based on last year’s tax (certain higher-income taxpayers) |
110% of the prior year’s tax |
Source: Internal Revenue Service, Estimated Tax FAQs and 2026 Publication 505.
That is often referred to as a safe-harbor approach.
But there is an important difference between intentionally using a safe harbor and simply repeating last quarter’s payment because nobody has run the numbers.
One is a strategy.
The other is a guess.
Your Income Probably Did Not Arrive in Four Equal Pieces
This is especially relevant for people whose income changes throughout the year.
• Maybe your medical practice had a stronger summer than expected.
• Maybe a large consulting contract came through.
• Maybe your business added employees, purchased equipment, or had expenses that were not part of the original forecast.
• Maybe you sold an investment.
• Maybe your spouse received a bonus.
• Maybe interest income is materially higher than it was a few years ago.
• Maybe you made a large charitable gift.
Maybe none of those things happened, but your income simply looks very different today than it did when the first estimated payment was calculated in April.
The calendar may divide the year into payment periods.
Your financial life rarely cooperates by dividing itself neatly into quarters.
That is why estimated taxes should ideally be connected to an actual picture of what has happened so far and what the rest of the year is expected to look like.
Filing Taxes and Planning Taxes Are Two Different Things
Most people think about taxes after the year is over.
By then, the job is largely historical.
Here is what you earned. Here is what you deducted. Here is what you owe.
Good tax planning asks a different question:
What decisions are still available while the year is happening?
That distinction matters.
There are financial decisions that may affect taxable income, retirement savings, charitable giving, business cash flow, investment income, and the timing of certain expenses.
Not every strategy is appropriate for every person, and many require coordination among financial, tax, legal, and retirement-plan professionals.
But you cannot evaluate an option you did not know existed until the following April.
Consider the Business Owner Who Is Having a Very Good Year
Imagine a business owner who expected to earn $300,000 this year.
By September, it is becoming clear that the number could be closer to $500,000.
That is good news.
It is also information.
If the estimated-tax strategy is still operating from assumptions made six months ago, the payments may no longer reflect the reality of the business.
More importantly, the change in income may create planning conversations that were not relevant at the beginning of the year.
• Does the business already have the right retirement-plan structure?
• Is there room for additional retirement savings?
• Are there charitable goals that were already part of the family’s plan?
• Are there business expenditures planned for later in the year?
• Are investment gains or losses creating additional tax considerations?
The goal is not to manufacture deductions for the sake of avoiding taxes.
The goal is to see the whole picture before the year is over.
One Example: The Cash Balance Plan
For certain profitable businesses and self-employed professionals, particularly those with consistently high income, one conversation may involve a cash balance pension plan.
A cash balance plan is a type of defined benefit retirement plan. Unlike a typical 401(k), the retirement benefit is determined under a formula, and an actuary is generally involved in determining required funding. The IRS notes that defined benefit plans can allow businesses to contribute and potentially deduct more than they could under defined contribution plans, although they are also more complex and costly to establish and maintain.
For the right business owner, that can make a significant difference.
It can potentially allow substantially more money to be directed toward retirement while also affecting the business’s taxable-income picture, subject to the plan design, actuarial calculations, employee demographics, deduction rules, and other requirements.
For the wrong business owner, it may be entirely inappropriate.
These plans involve real funding obligations and administrative complexity. Contributions are not simply a number the owner picks in December because a tax bill looks uncomfortable. An actuary determines funding requirements, and the business needs to evaluate whether it can support those commitments over time.
September 15 can be a useful reminder that there are only a few months left to understand what kind of year you are actually having.
Do Not Let the Tax Payment Become the Planning Process
There is a common pattern among successful professionals and business owners.
Income comes in. Money accumulates in the business or bank account. An estimated-tax date approaches. Someone provides a number. The check gets written. Then everyone goes back to work.
That may satisfy the immediate deadline.
But the payment itself should not be the entire tax-planning process.
A better process connects the tax projection to the rest of the financial picture.
• How much cash does the business need?
• What are you saving for retirement?
• What large expenses are coming?
• How has investment income changed?
• What has already been withheld or paid?
• What does the year-end projection look like?
• What decisions still need to be made before December 31?
Those questions turn estimated taxes from a quarterly interruption into part of a larger financial plan.
September Is Giving You Information
September 15 is not the end of the year.
That is precisely why it matters.
There is still time left on the calendar.
By now, you have eight months of real-world information about your income, expenses, business, investments, and life.
The year is no longer a projection made in January. But it is not finished either.
That makes September a valuable middle ground.
There may be nothing that needs to change. Your estimated payments may be perfectly appropriate. Your retirement plan may already be exactly what it should be. Your tax professional may have everything dialed in.
That is a perfectly good outcome.
But it should be the result of looking.
Because when September 15 arrives, writing a check is easy. Knowing why you are writing that check is the part that deserves a little more thought.
Sources
Internal Revenue Service, Third Quarter Tax Calendar, including the September 15, 2026 estimated-tax deadline for individuals. https://www.irs.gov/businesses/small-businesses-self-employed/2026-tax-calendar
Internal Revenue Service, Estimated Tax FAQs and 2026 Publication 505, Tax Withholding and Estimated Tax. https://www.irs.gov/publications/p505
Internal Revenue Service, Defined Benefit Plan guidance and 2026 retirement-plan limits. https://www.irs.gov/retirement-plans/defined-benefit-plan
U.S. Department of Labor, Cash Balance Pension Plans guidance. https://www.dol.gov/agencies/ebsa/key-topics/retirement-benefits/cash-balance-pension-plans
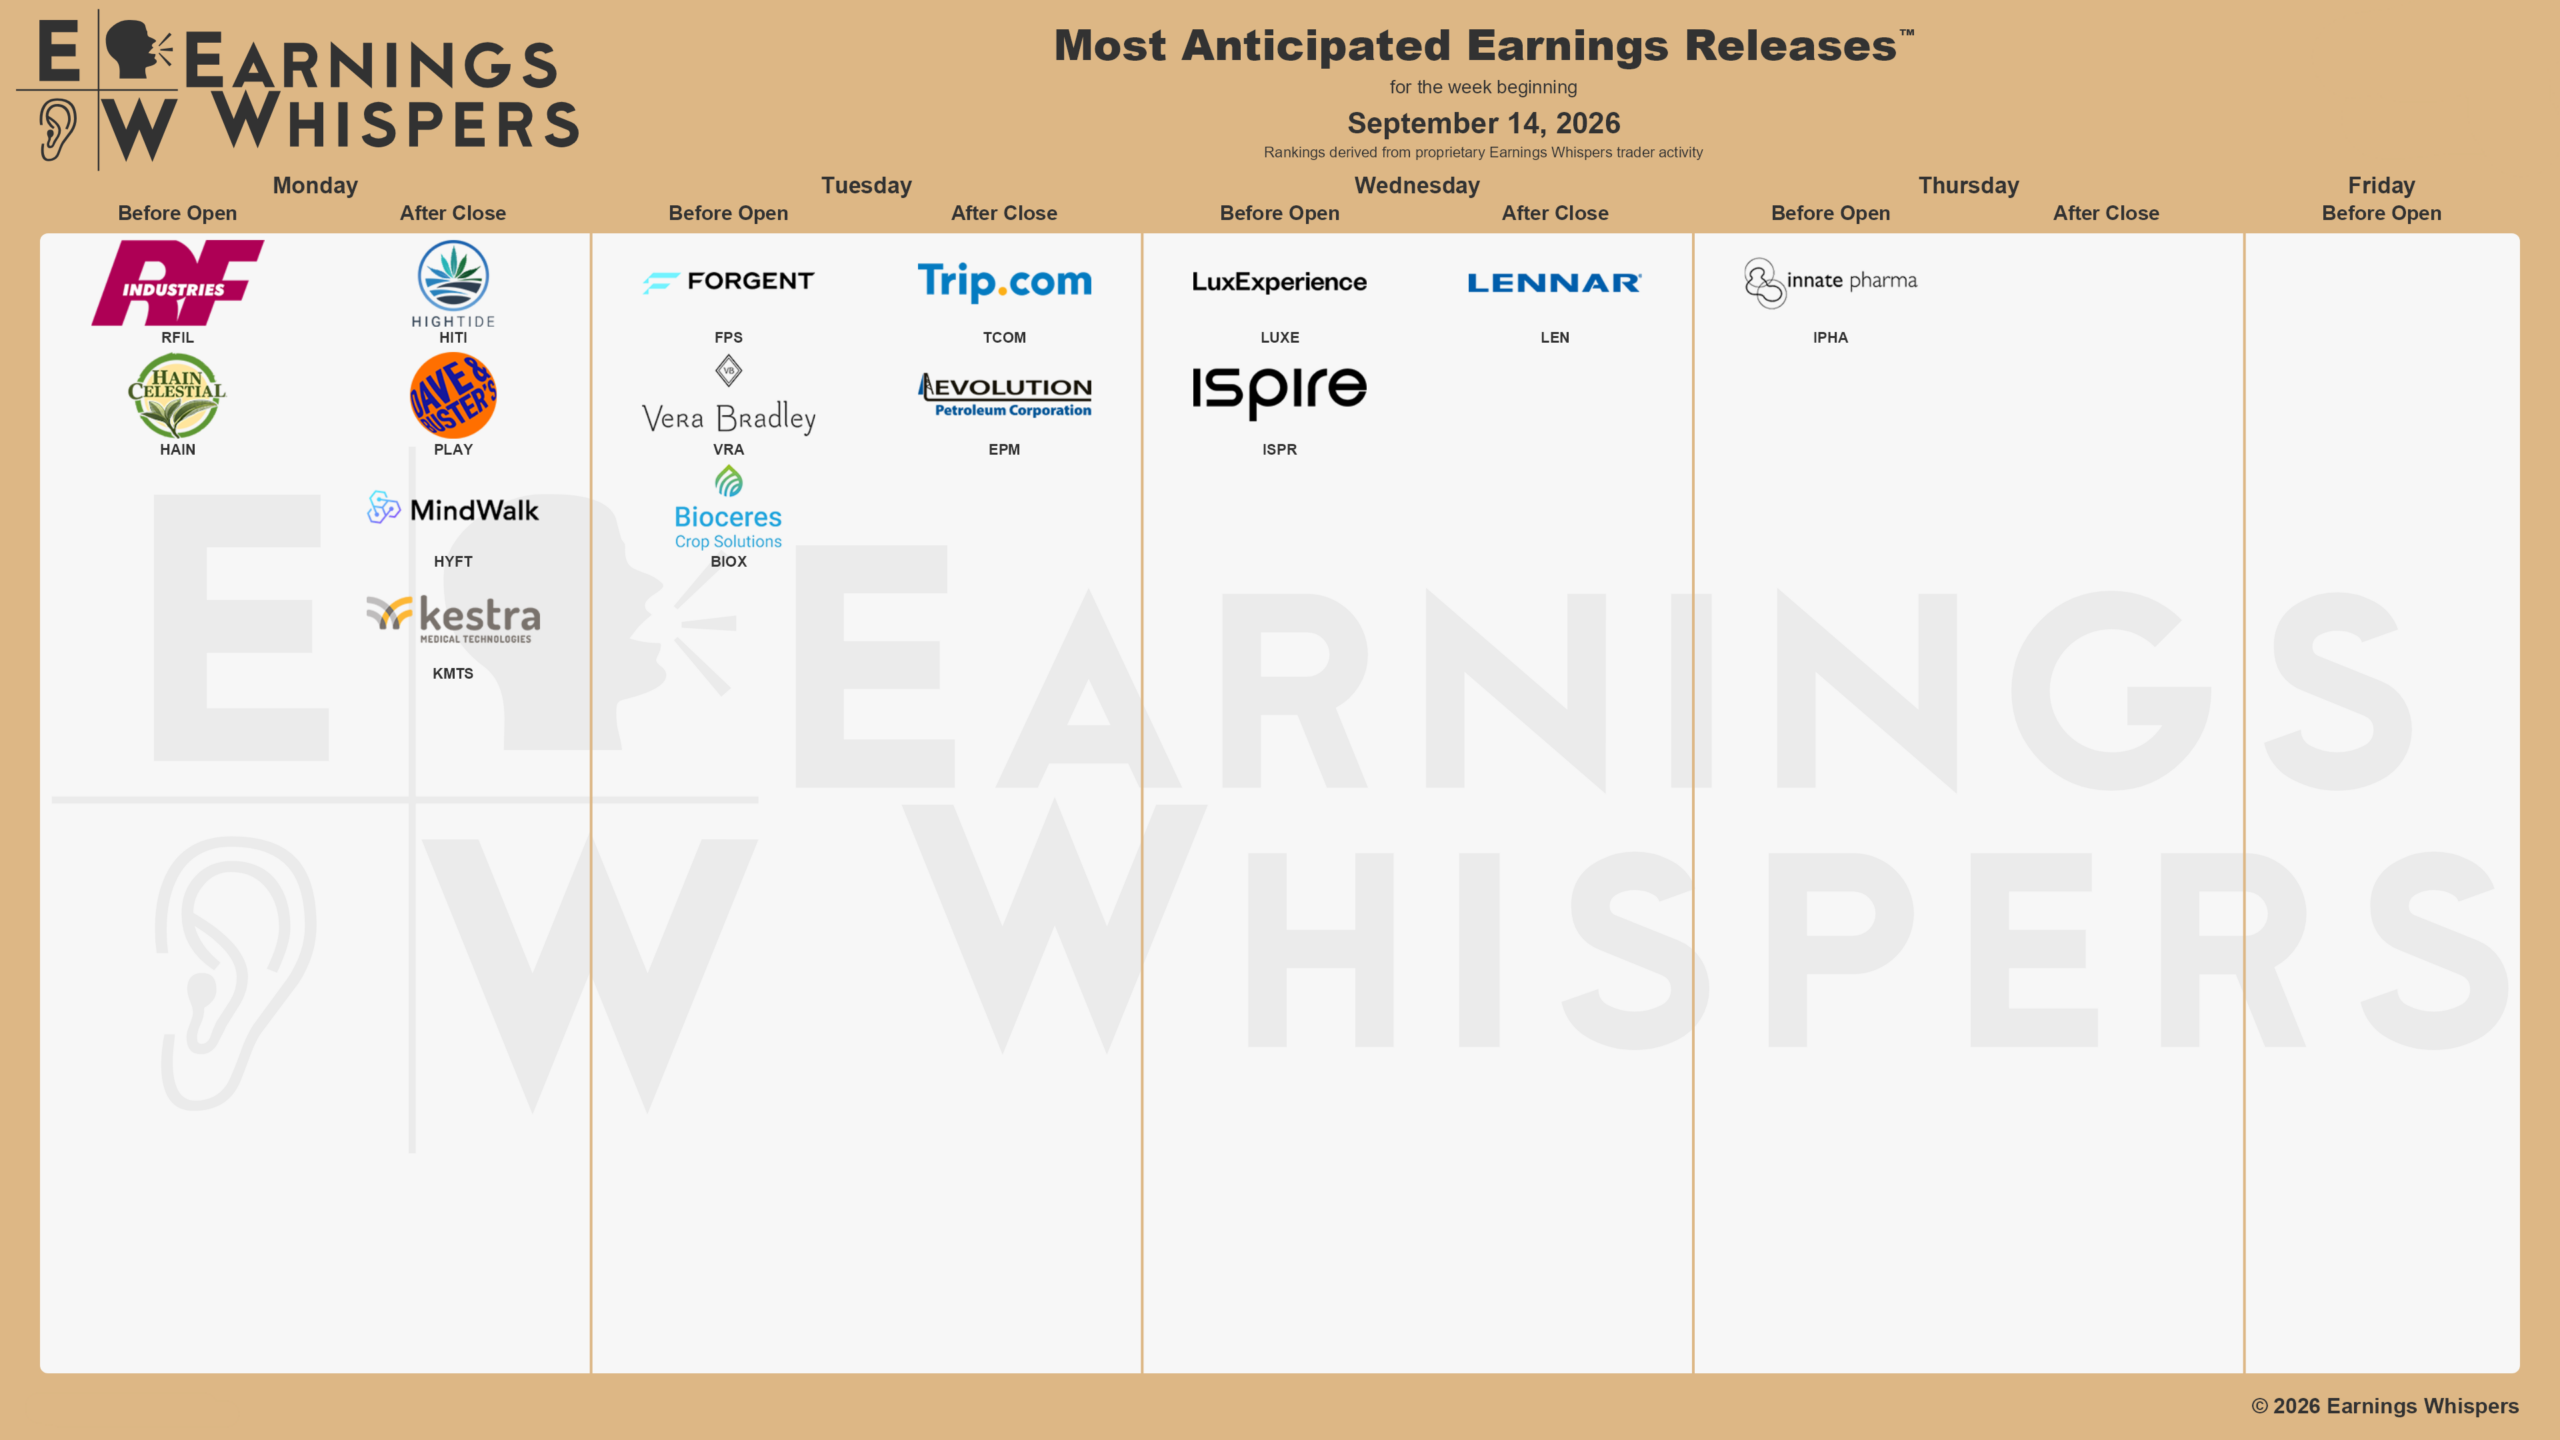
Stock Market Calendar This Week:
| Time (ET) | Report |
| Monday, Sep. 14 | |
| No events scheduled | |
| Tuesday, Sep. 15 | |
| 8:30 AM | Empire State Manufacturing Survey |
| TBA | U.S. Federal Open Market Committee meeting |
| Wednesday, Sep. 16 | |
| 8:30 AM | Retail Sales |
| 8:30 AM | Import Prices |
| 10:00 AM | Manufacturing & Trade: Inventories |
| 10:00 AM | NAHB Housing Market Index |
| 2:00 PM | Federal Reserve economic projections |
| 2:00 PM | U.S. interest rate decision |
| Thursday, Sep. 17 | |
| 8:30 AM | Housing Starts |
| 8:30 AM | Philadelphia Fed Business Outlook Survey |
| 8:30 AM | Weekly Jobless Claims |
| 10:00 AM | Pending Home Sales Idx, M/M% |
| Friday, Sep. 18 | |
| 9:15 AM | Industrial Production, M/M% |
| 9:15 AM | Capacity Utilization % |
| 10:00 AM | Leading Indicators |
About Amit: I am a first generation American, the son of a working-class Indian family, and I lived through my parents’ struggle to find their place in this country, to put down roots that would sustain them as well as their children in a new land. As they encouraged me to excel in school and fostered my hobbies and interests, I was keenly aware of the dynamic between them. I understood that there was a difference between where they came from individually and where we were now. They worked hard in their individual capacities, but they weren’t always on the same page about financial issues – and that can make or break a family’s future. I didn’t know it at the time, but this laid the groundwork for my passion towards financial services and helping families succeed.
IMPORTANT NOTICE AND DISCLOSURE
The information and material contained in this communication is confidential and intended for the recipient addressee named. If you are not the intended recipient please delete the message and notify the sender immediately.
NewEdge Advisors, LLC is an Investment Adviser registered with the Securities and Exchange Commission. Any information provided has been obtained from sources considered reliable, but we do not guarantee the accuracy or the completeness of any description of securities, markets or developmentsmentioned. As a precautionary measure, we cannot rely on e-mail requests to authorize, direct or effect the purchase or sale of any security, wire transfer, or to affect any other transactions. Such requests, orders, or other instructions sent by email should be confirmed verbally, prior to their anticipated execution. We are unable to ensure email sent to you from us, or sent from you to us will be received. Please contact us at 845-652-3449 if there is any change in your financial situation, needs, goals or objectives, or if you wish to initiate any restrictions on the management of the account or modify existing restrictions. Additionally, we recommend you compare any account reports from NewEdge Advisors LLC with the account statements from your Custodian. Please notify us if you do not receive statements from your Custodian on at least a quarterly basis. Our current disclosure brochure, Form ADV Part 2, is available for your review upon request. This disclosure brochure, or a summary of material changes made, is also provided to our clients on an annual basis. This material was prepared with the assistance of AI. All content has been reviewed, edited, and approved by Forefront Wealth Planning prior to use. This is general education and not a substitute for personalized tax, legal, or investment advice. Your situation should be reviewed with the appropriate professionals before taking action. Advisory services offered through NewEdge Advisors, LLC, a registered investment adviser.